Money management is an important life skill, but understanding how much money you can actually spend after paying your bills is equally important. Earning a good salary does not always mean having enough money for shopping, entertainment, travel, or personal goals. Your income must first cover essential expenses such as housing, groceries, transportation, utilities, and taxes.
This is where discretionary income becomes important.
Discretionary income helps you understand how much money remains after covering your necessary expenses. It gives you a clearer picture of your financial flexibility and helps you make better decisions about spending, saving, and investing.
In this guide, we will explore what discretionary income means, how to calculate it, practical examples, its importance, and how it differs from disposable income.
What Is Discretionary Income?
Discretionary income is the amount of money a person has left after paying taxes and essential living expenses. It is the money available to spend, save, or invest according to personal preferences and financial goals.
In simple words, discretionary income is the extra money you have after taking care of your basic needs.
For example, imagine someone earns $5,000 per month. After paying $1,000 in taxes and $3,000 in essential expenses, the person has $1,000 remaining.
That remaining $1,000 is their discretionary income.
It can be used for activities such as:
- Going to restaurants and cafes.
- Shopping for nonessential products.
- Planning vacations and trips.
- Watching movies or attending concerts.
- Purchasing entertainment subscriptions.
- Investing in hobbies and personal interests.
- Saving for future goals.
However, discretionary income does not necessarily mean money that should be spent immediately. It can also be used to build savings, invest, or pay down debt.
Discretionary Income Formula
The formula for calculating discretionary income is straightforward.
Discretionary Income Formula
Discretionary Income = Gross Income – Taxes – Essential Expenses
Another way to calculate it:
Discretionary Income = Disposable Income – Essential Expenses
Disposable income generally refers to income remaining after taxes.
Where:
- Gross Income: Total earnings before taxes and other deductions.
- Taxes: Income taxes paid or withheld from earnings.
- Essential Expenses: Necessary costs such as housing, groceries, utilities, healthcare, and transportation.
- Disposable Income: Income remaining after income taxes.
The amount left after subtracting taxes and essential expenses represents discretionary income.
How to Calculate Discretionary Income
You can calculate discretionary income by following four simple steps.
Step 1: Calculate Your Gross Income
Start by identifying your total monthly income before taxes. Include your salary, wages, business earnings, and other regular income sources.
Step 2: Subtract Taxes
Calculate the amount deducted or paid in taxes. This includes applicable federal, state, and local income taxes.
Step 3: Calculate Essential Expenses
Add up the costs of necessary living expenses, including rent, groceries, transportation, utilities, healthcare, and required insurance payments.
Step 4: Subtract Essential Expenses and Taxes
Subtract your taxes and essential expenses from your gross income. The remaining amount is your discretionary income.
Discretionary Income Example
Let’s understand the concept with a practical monthly income example.
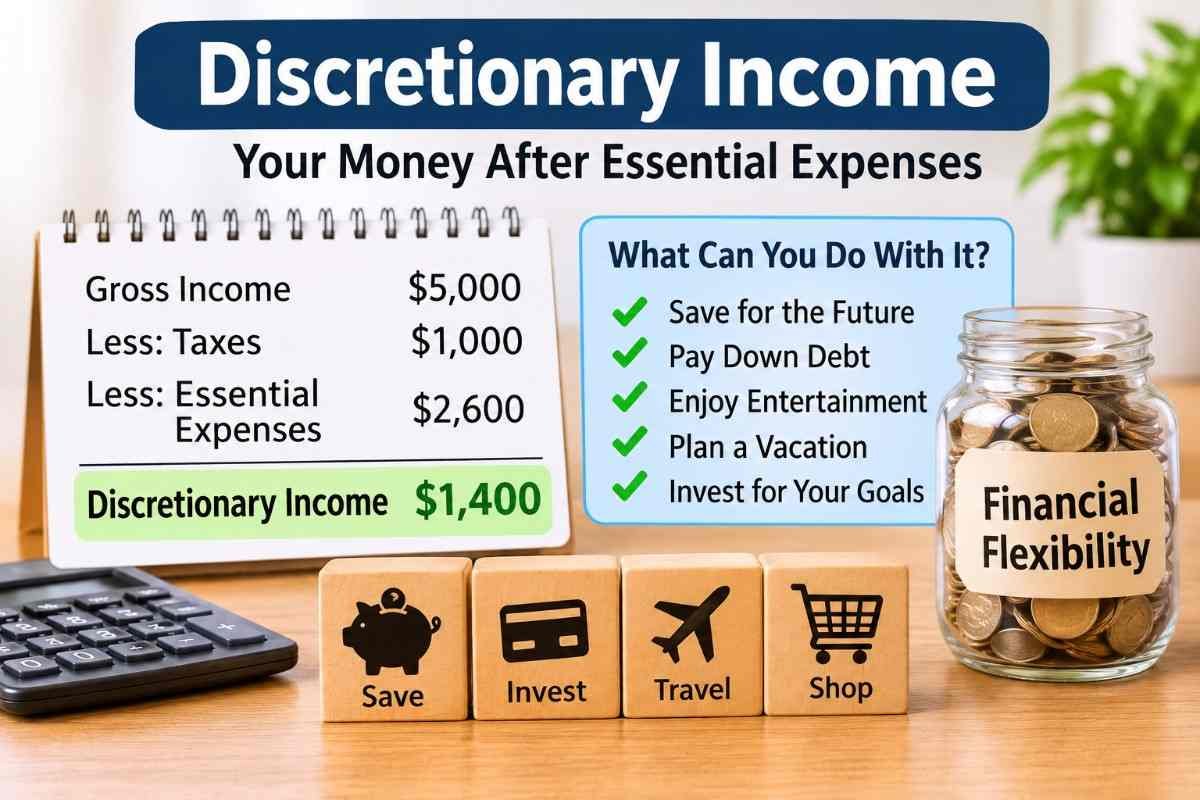
Imagine Sarah works as a marketing professional in the United States and earns $5,000 per month before taxes.
Her monthly financial details are:
| Income and Expenses | Amount |
|---|---|
| Gross monthly income | $5,000 |
| Taxes | $1,000 |
| Rent | $1,400 |
| Groceries | $450 |
| Utilities | $200 |
| Transportation | $300 |
| Healthcare and insurance | $250 |
| Total essential expenses | $2,600 |
Now calculate her discretionary income:
- Gross income = $5,000
- Taxes = $1,000
- Essential expenses = $2,600
Calculation:
$5,000 – $1,000 – $2,600 = $1,400
Sarah’s monthly discretionary income : $1,400
This is the amount remaining after taxes and the listed essential expenses.
Sarah can use this $1,400 for additional savings, entertainment, shopping, investments, travel, or other financial goals.
This example shows how discretionary income helps people understand their actual financial flexibility rather than focusing only on their salary.
What Are Examples of Discretionary Expenses?
Discretionary expenses are costs associated with nonessential products, services, and activities. People can generally reduce or avoid these expenses without immediately affecting their basic living requirements.
Common examples include:
- Entertainment: Movie tickets, concerts, video games, and streaming subscriptions.
- Dining Out: Restaurant meals, coffee shops, and ordering food for enjoyment.
- Travel and Vacations: Weekend trips, international holidays, and luxury hotel stays.
- Shopping: Designer clothing, accessories, and unnecessary purchases.
- Hobbies: Photography equipment, musical instruments, and recreational activities.
- Personal Luxury: Expensive watches, premium gadgets, and luxury products.
- Subscriptions: Optional memberships and entertainment services.
- Recreation: Theme parks, sporting events, and leisure activities.
Whether an expense is essential or discretionary can depend on an individual’s circumstances. For example, internet access may be essential for someone working remotely but optional in another situation.
What Are Essential Expenses?
Essential expenses are the necessary costs people need to cover to maintain their basic living standards and meet important financial obligations.
These expenses are generally paid before discretionary spending.
Some common examples include:
- Housing: Rent, mortgage payments, and basic housing costs.
- Groceries: Food and other basic household supplies.
- Utilities: Electricity, water, heating, and essential internet or phone services.
- Transportation: Necessary commuting expenses, public transportation, or vehicle costs.
- Healthcare: Medical appointments, necessary medications, and health insurance.
- Insurance: Required or important health, auto, and home insurance.
- Debt Obligations: Required minimum payments on loans and credit cards.
Understanding the difference between essential and discretionary expenses is important when creating a realistic household budget.
Why Is Discretionary Income Important?
Understanding discretionary income is useful because it shows how much financial flexibility a person has after covering necessary expenses.
Here are some important reasons to understand it.
1. Helps Create a Better Budget: Knowing your discretionary income makes it easier to divide your money between savings, optional purchases, and personal goals.
2. Encourages Smart Spending: It helps you understand how much you can spend on nonessential items without affecting your essential financial responsibilities.
3. Supports Financial Planning: You can use discretionary income to plan for future expenses, investments, vacations, and other financial goals.
4. Helps Build Emergency Savings: Setting aside part of your discretionary income can help you prepare for unexpected expenses.
5. Improves Debt Management: Extra money can be used to pay more than the minimum required on certain debts, potentially reducing interest costs.
6. Provides Financial Flexibility: A higher amount of discretionary income generally gives individuals more freedom to make lifestyle choices.
7. Helps Identify Spending Habits: Tracking this income can reveal whether too much money is going toward unnecessary purchases.
8. Supports Long-Term Goals: You can direct extra funds toward retirement savings, education, homeownership, or other important goals.
Factors That Affect Discretionary Income
Several personal and economic factors can influence how much discretionary income an individual has.
1. Salary and Earnings: Higher earnings may increase discretionary income if essential expenses do not rise at the same rate.
2. Cost of Living: People living in expensive cities may spend more on housing, transportation, and groceries, leaving less money for optional expenses.
3. Taxes: Changes in tax obligations can affect the amount of income available after taxes.
4. Housing Costs: Higher rent or mortgage payments can reduce the money available for discretionary spending.
5. Family Size: Supporting children or other family members can increase essential household expenses.
6. Debt Payments: Required loan and credit card payments can reduce the amount of money available for other financial priorities.
7. Inflation: Rising prices for food, fuel, housing, and other necessities can reduce purchasing power and discretionary income.
8. Employment Stability: Changes in working hours, salary, or employment status can affect monthly income and financial flexibility.
How to Increase Discretionary Income
Increasing discretionary income does not always require finding a higher-paying job. Making better financial decisions and managing necessary expenses can also help.
Consider these practical strategies:
- Increase Your Earnings: Look for career advancement opportunities, additional work, or ways to develop valuable professional skills.
- Review Housing Expenses: Consider whether your current housing costs fit comfortably within your budget.
- Reduce Unnecessary Bills: Review subscriptions, memberships, and services you rarely use.
- Plan Grocery Shopping: Prepare shopping lists and compare prices to manage food expenses.
- Use Public Transportation: Where practical, public transportation or carpooling may reduce commuting costs.
- Avoid Impulse Purchases: Give yourself time to consider nonessential purchases before spending money.
- Review Insurance Costs: Compare suitable insurance options while maintaining appropriate coverage.
- Create a Monthly Budget: Monitor income and expenses to identify opportunities to improve your financial situation.
The goal is not to eliminate every enjoyable purchase. Instead, it is to create a healthy balance between necessary expenses, savings, and lifestyle choices.
How Should You Use Your Discretionary Income?
Once you calculate your discretionary income, the next step is deciding how to use it responsibly.
There is no single correct method because everyone’s financial circumstances and priorities are different.
Here are some common ways to allocate it:
| Financial Priority | Possible Use |
|---|---|
| Emergency savings | Build a financial safety net |
| Debt repayment | Pay extra toward high-interest debt |
| Investments | Invest according to your financial goals and risk tolerance |
| Retirement | Increase retirement contributions |
| Education | Pay for courses and professional development |
| Entertainment | Enjoy movies, restaurants, and hobbies |
| Travel | Save for vacations and personal experiences |
A balanced approach allows you to enjoy your money while also preparing for future needs.
Advantages of Discretionary Income
1. Financial Freedom: Discretionary income gives individuals more freedom to spend money on personal interests, hobbies, travel, and entertainment.
2. Encourages Savings: Extra income can be set aside for emergency funds, future purchases, and long-term financial goals.
3. Supports Investments: Individuals can use discretionary income to invest in stocks, mutual funds, retirement accounts, or other suitable investment options.
4. Improves Lifestyle: Having extra money makes it easier to enjoy restaurants, vacations, recreational activities, and other nonessential purchases.
5. Helps Pay Off Debt: Discretionary income can be used to make additional debt payments and potentially reduce interest costs.
6. Provides Financial Flexibility: It allows people to manage unexpected opportunities and personal expenses without affecting their basic needs.
7. Supports Personal Development: Extra money can be spent on educational courses, professional training, books, and skill development.
8. Improves Financial Planning: Tracking discretionary income helps individuals understand their spending habits and make better budgeting decisions.
Disadvantages of Discretionary Income
1. Encourages Overspending: Having extra money may tempt people to purchase unnecessary products and services.
2. Can Lead to Poor Financial Habits: Spending most discretionary income on entertainment and luxury items can reduce opportunities to build savings.
3. Affected by Inflation: Rising costs of essential goods and services can reduce the amount of money available for discretionary spending.
4. Varies With Income: People with unstable earnings may experience significant changes in their discretionary income from month to month.
5. Creates Lifestyle Inflation: As income increases, individuals may increase their spending on luxury products instead of improving their financial security.
6. May Create Financial Pressure: Poor spending decisions can lead to credit card debt and other financial difficulties.
7. Not Equal for Everyone: People with higher housing costs, family responsibilities, or medical expenses may have very little discretionary income.
8. Can Be Difficult to Calculate: Unexpected bills and irregular essential expenses can make it challenging to estimate the actual amount available.
Discretionary Income in Economics
Discretionary income is not only important for personal budgeting; it also has a connection to the wider economy.
When households have more money available after covering essential expenses, they may have greater flexibility to purchase nonessential goods and services.
For example, a household with more discretionary income might spend more on:
- Restaurants and entertainment.
- Travel and tourism.
- Electronics and technology.
- Fashion and luxury products.
- Recreational activities.
This spending can contribute to business revenue and economic activity.
On the other hand, when essential expenses increase faster than household income, people may reduce spending on nonessential products and services.
For example, if rent, groceries, and transportation costs increase significantly, a family may decide to postpone a vacation or cancel entertainment subscriptions.
This is one reason discretionary income is useful when studying consumer behavior and household spending patterns.
Discretionary Income and Student Loans
Discretionary income also has a specific meaning in the United States federal student loan system.
Certain income-driven student loan repayment plans use a government-defined calculation of discretionary income to determine payment amounts or eligibility.
However, this calculation is not necessarily the same as the personal budgeting formula discussed earlier.
For federal student loans, the applicable calculation can depend on the repayment plan, adjusted gross income, family size, and federal poverty guidelines.
Therefore, borrowers should check the current rules for their specific repayment plan rather than assuming that their monthly leftover money determines their student loan payment.
You can learn more through the official Federal Student Aid website.
Common Mistakes People Make When Understanding Discretionary Income
Discretionary income is a simple concept, but some common mistakes can lead to inaccurate financial calculations.
1. Confusing Gross Income With Take-Home Income: Gross income is calculated before taxes, while take-home income reflects deductions from earnings.
2. Ignoring Essential Expenses: Calculating discretionary income without including important household expenses can produce an unrealistic figure.
3. Treating All Remaining Money as Spending Money: Discretionary income can also be saved or invested rather than spent entirely.
4. Forgetting Irregular Expenses: Annual insurance payments, occasional medical costs, and necessary repairs should be considered when creating a realistic budget.
5. Using the Same Calculation for Every Purpose: Personal budgeting calculations and government student loan calculations may use different methods.
6. Ignoring Changes in Living Costs: A calculation made several months ago may no longer reflect your current financial situation.
Conclusion
Discretionary income is an important personal finance and economics concept that helps explain how much money remains after paying taxes and essential living expenses.
Understanding this concept can help individuals create realistic budgets, control unnecessary spending, build savings, and plan for future financial goals.
Whether you are a student learning basic economics or an adult managing household finances, knowing how discretionary income works can help you make more informed financial decisions.
The most important lesson is that earning money is only one part of financial management. Understanding how much money remains after covering your necessities is equally important.
FAQ’s
Is discretionary income the same as disposable income?
No. Disposable income is generally income after taxes, while discretionary income is what remains after taxes and essential living expenses.
Can discretionary income be negative?
Yes. If essential expenses exceed after-tax income, a person’s calculated discretionary income can be negative, indicating a shortfall.
Is saving considered discretionary income?
Yes. Discretionary income can be allocated toward savings, investments, debt repayment, or optional purchases.
Why is discretionary income important in economics?
It helps explain household purchasing power, consumer spending decisions, and demand for nonessential goods and services.
Does higher income always mean higher discretionary income?
No. Higher housing costs, taxes, debt payments, and other essential expenses can reduce the amount of discretionary income.
How can I improve my discretionary income?
You can improve it by increasing your earnings, managing essential expenses, reducing unnecessary costs, and creating a realistic budget.
What does 10% of discretionary income mean?
10% of discretionary income means taking one-tenth of the money left after paying taxes and essential living expenses. For example, if your discretionary income is $1,000, then 10% equals $100.
Is discretionary income net income?
No. Net income is generally the money remaining after taxes and payroll deductions, while discretionary income is what remains after paying taxes and essential living expenses.
What is a good amount of discretionary income?
A good amount depends on your income, living costs, family size, and financial goals. Having enough discretionary income to cover savings, debt repayment, and personal spending without financial stress is a healthy goal.
What is another name for discretionary income?
Discretionary income is sometimes called surplus income or income available for nonessential spending. However, these terms may have different meanings depending on the financial context.
Sources / References:
Disclaimer:
This article is for educational and informational purposes only. It does not constitute professional financial, tax, or investment advice. Consult a qualified financial professional for guidance based on your circumstances.
Also Read: