Contents :
- Intra-State & Inter-State Supply.
- Extent & Commencement of GST Law.
- Levy & Collection of CGST & IGST (Sec 9 of
CGST Act & Sec 5 of IGST Act). - Meaning of Reverse Charge Mechanism (RCM).
- List of Services And Goods Notified Under RCM [Sec 9(3) Of
CGST Act & 5(3) Of IGST Act]. - Rates of GST.
- Composition Scheme [Section 10].
- Conditions & Restrictions for Composition Levy
[Rule 5]. - Validity of Composition Levy (Section 10(3) R/W
Rule 6). - Penalty For Irregular Availment of Composition
Scheme Sec 10(5) R / W Rule 6(4) & 6(5). - Intimation of Opting for Composition Levy Rules 3
& 4. - Composition Scheme for Service Providers (NN
2/2019).
IMPORTANT DEFINITIONS :
Exempt Supply (Sec 2(47) of CGST Act) :
- Means supply which attracts nil rate of tax).
- Which may be wholly exempt from tax u/s 11, or u/s 6 of IGST Act.
- Includes non-taxable supply.
Reverse charge [Section 2(98) of CGST Act] :
- Liability to pay tax is on ‘recipient’ of supply of G/&S instead of supplier of such G/&S.
India :
- Territory of India &,its territorial waters (TWI).
- Seabed & sub-soil underlying such waters.
- Continental shelf.
- Exclusive economic zone or any other maritime zone.
- Air space above its territory & TWI.
Intra-state & Inter-State supply :
|
Particulars |
Intra-State Supply |
Inter-State Supply |
|
Meaning |
Location of supplier & PoS are in i) Same UT ii) Same State |
Location of supplier & PoS are in i) Different States ii) Different UTs iii) A State & a UT [MH > A&N] |
|
Applicability |
CGST + SCGT/(UTGST for UTs) |
IGST |
EXTENT & COMMENCEMENT OF GST LAW :
LEVY & COLLECTION OF CGST & IGST (Sec 9 of CGST Act & Sec 5 of IGST Act) :
|
Section |
Levy & Collection |
||||||
|
9(1) |
Levy of CGST on
|
||||||
|
9(2) |
No Levy of GST on |
||||||
|
9(3)
|
Power of Government to specify
|
||||||
|
9(4) (AMD) |
Tax under RCM is payable on-Notified category of Inward Supplies, of
|
||||||
|
9(5) |
Payment of GST by electronic commerce
Notified Services are :
|
Meaning of ECO :
- ECO is any person who owns/operates/manages an electronic platform for supply of G/&S.
- ECO display products & services on their electronic portal which are actually supplied by some other person to the consumer.
- Consumers buy such goods/services through these portals.
- On placing order for a particular product/service, actual supplier suppliers supplies selected product / service to consumer.
- Price is collected by ECO from consumer and thereafter given to actual supplier after deduction their commission.
WHAT IS THE REVERSE CHARGE MECHANISM (RCM) :
- Reverse charge means the liability to pay tax is on the recipient of supply of G/S instead of the supplier.
- Generally, supplier is liable to pay GST. However, under RCM, liability to pay GST is on recipient of G/S.
- However, underlying principle of an indirect tax is that burden of such tax has to be ultimately passed on to the recipient. GST being an indirect tax, this principle holds good for GST. Therefore, under RCM, only the compliance requirements, (i.e. to obtain registration under GST, deposit the tax with the Government filing returns, etc.) have been shifted from supplier to recipient.
GOODS NOTIFIED UNDER RCM [Sec 9(3) of CGST Act & 5(3) of IGST Act] :
- Cashewntats (not shelled/peeled).
- Bidi wrapper leaves & tobacco leaves.
- Supply of Lottery, Silk yarn, used vchicles.
- Seized and Conficated goods.
- Old &used goods.
- Waste & scrap.
- Raw cotton, etc.
SERVICES NOTIFIED UNDER RCM [Sec 9(3) of CGST Act & 5(3) of IGST ACT] :
|
SN. |
Nature of Service |
Supplier (BY) |
Recipient [Person liable to pay GST] |
|
1 |
Goods Transport Agency (GTA) Goods by Road
|
Goods Transport Agency paying 2.5% CGST |
|
|
|
AMD : NO RCM on Transportation services provided by GTA to Note: Above services have been simultaneously exempted from |
||
|
|
Meaning of Recipient : Person who pays or is liable to pay freight for the |
||
|
Q. ABC Ltd. availed service of XYZ Ltd. (GTA) Ans: GST shall be paid by ABC Ltd. under RCM u/s |
|||
|
2. |
Legal Services |
Individual Advocate (including senior advocate or firm of advocates) |
Business Entity located in TT. |
|
3 |
Services by Arbitral Tribunal |
Arbitral Tribunal |
Business Entity located in TT. |
|
4 |
Sponsorship |
Any Person |
Body Corporate or P’ship Firm in TT |
|
Q.ABCLtd. Ans: |
|||
|
5 |
Services supplied by CG, SG, UT/LA |
CG, SG, UT, LA |
Business Entity located in TT. |
|
|
Excluding [No RCM in case of supply of these services] a) Renting of Immovable Property b) Specified services:
|
||
|
5A |
Services supplied by CG, SG, UT or LA way of renting of immovable |
CG, SG, UT or LA |
Any Registered Person under GST |
|
Q. Rental income received by Tamil Nadu State Government from renting an Ans : In case of Services supplied by CG/SG/UT/LA by way of renting of |
|||
|
5B |
Services of Transfer of development rights or Floor Space Index (FSI) for |
Any person |
Promoter |
|
5C |
Long term lease of land(> 30 years) against consideration in the form |
Any person |
Promoter |
|
6 |
Services supplied by a Director |
Director |
Company or Body Corporate |
|
7 |
Services supplied by Insurance Agent |
Insurance Agent |
Insurance Company located in TT. |
|
Q. Insurance company pay Rs. 1,00,000 commission to Mr. A whose turnover Ans. : Insurance company will be liable to pay GST under reverse charge |
|||
|
8 |
Services supplied by Recovery Agent |
Recovery agent |
Banking company or financial institution or NBFC located in TT. |
|
9 |
Transfer/permitting use enjoyment of copyright relating to original |
Author, music composer, Photographer, Artist etc. |
Publisher, Music company, Producer etc. located in taxable territory. |
|
10 |
Supply of Services by Members of overseeing Committee |
Members of Overseeing Committee constituted by RBI |
RBI |
|
11 |
Services supplied by Individual Direct Selling Agents (DSAs) |
Individual Direct Selling Agents (DSAs) other than BC, P’ship firm or LLP |
Banking company or NBC in TT. |
|
12 |
Services provided by Business facilitator |
Business facilitator |
Banking company, located in TT. |
|
13 |
Services provided by Agent of Business correspondent |
Agent of Business correspondent |
Business Correspondent located in TT |
|
14 |
Security Services (Services Supply of security personnel) |
Any Person other than BC |
Any Registered Person, located in TT |
|
|
Note : Tax has to be paid under RCM on |
||
|
|
However, nothing contained in this entry shall apply to :
|
||
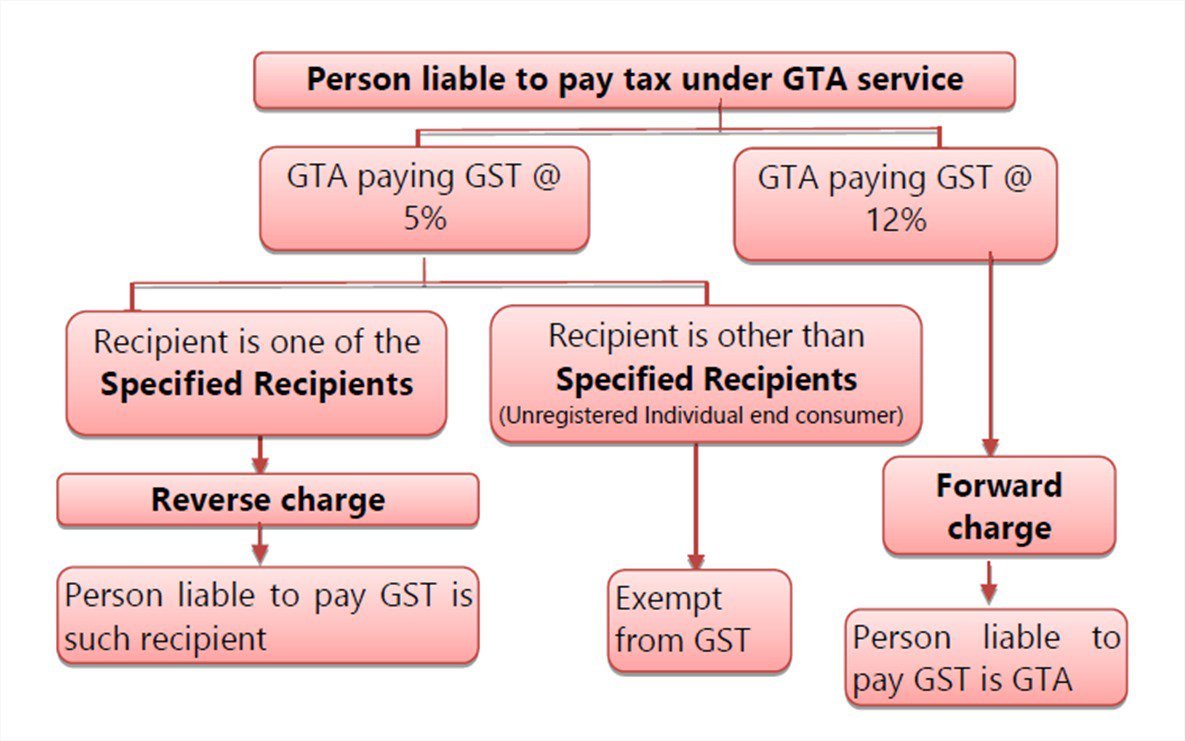
Q. State the person liable to pay GST provided recipient is located in taxable territory & it is intra-state supply :
RATES OF GST :
CLASSIFICATION OF GOODS :
- Classification of goods means identification of the tariff item, sub-heading, heading & chapter in which a particular product will be classified.
- Tariff item, sub-heading, heading & chapters referred in the Schedules of rate notification for goods under GST a the Tariff item, sub-heading, heading & chapters of the First Schedule to the Customs Tariff Act, 1975.
- Indian Customs Tariff is based on HSN. HSN stands for Harmonized System of Nomenclature.
- It is a multipurpose international product nomenclature developed by the World Customs Organization (WCO) for the purpose of classifying goods across the World in a systematic manner.
- It comprises of about 5,000 commodity groups; each identified by a 6-digit code [code can be extended), arranged in a legal & logical structure & is supported by well-defined rules to achieve uniform classification.
- India has developed an 8-digit code of HSN.
- Along the lines of HSN, the Indian Customs Tariff has a set of Rules of Interpretation of the First Schedule & General Explanatory notes. These rules & the general explanatory notes give clear direction as to how the nomenclature in the schedule is to be interpreted. These Rules for Interpretation including section & chapter notes & the General Explanatory Notes of the First Schedule apply to the interpretation of the rate notification for goods under GST also.
- Consequently, under GST, goods are classified on the basis of HSN in accordance with the Rules for Interpretationd the Customs Tariff.
- Once classification fora product has becn determined on this basis, applicable rate has to be determined as per the rate prescribed in the rate notification issued under GST.
|
CGST |
0% |
0.125% |
1.5% |
2.5% |
6% |
9% |
14% |
|
SGST |
0% |
0.125% |
1.5% |
2.5% |
6% |
9% |
14% |
|
TOTAL |
0% |
0.250% |
3% |
5% |
12% |
18% |
28% |
CLASSIFICATION OF SERVICES :
- A new Scheme of Classification of Services has been devised under GST. It is a modified version of the United Nations Central Product Classification.
- Under this scheme, the services of various descriptions have been classified under various sections, headings & groups. Chapter 99 has been assigned for services. This chapter has following sections :
|
Section 5 |
Construction Services. |
|
Section 6 |
Distributive Trade Services; Accommodation, Food |
|
Section 7 |
Financial & related services; real estate |
|
Section 8 |
Business & Production Services. |
|
Section 9 |
Community, social & personal services & |
- Each section is divided into various headings which is further divided into Groups. Its further division is made in the form of Tariff item’/ Service Codes. Rate of tax is determined as per the Service Code in which the service is classified.
- Gambling Services, Services of admission to entertainment events/sporting event attract 28% GST.
- Services not covered under any specific heading are taxed @18% (CGST@9% & SGST @ 9%).
|
CGST |
0% |
2.5% |
6% |
9% |
14% |
|
SGST |
0% |
2.5% |
6% |
9% |
14% |
|
TOTAL |
0% |
5% |
12% |
18% |
28% |